GMC financing preapproval is worth exploring before you visit Vince's GMC in Burlington, Colorado, to shop for your next vehicle. You can prepare for the application process while comparing a new GMC Sierra, a new Terrain, or a used vehicle. What happens after you apply? A lender reviews your information and may request further details before offering specific loan terms. Knowing the steps can make your dealership visit more productive.
How GMC Financing Preapproval Works
Preapproval gives you an early view of possible financing, subject to lender review. Prequalification is another preliminary step, and lenders may use the two terms differently. Neither should be treated as a signed loan agreement. Therefore, read the disclosures attached to the application before submitting it.
The process begins when you provide identifying details, employment information, and financial information requested by the application. Next, a lender evaluates the submission against its lending criteria. The lender may respond with an initial decision, request supporting records, or require additional review. After you select a GMC, the vehicle's price and details may shape the final terms.
Will applying affect your credit score? It may, because a lender could use a hard credit inquiry. Some preliminary qualification tools use soft inquiries instead. However, the inquiry type must be confirmed in the terms of the specific application. Do not assume every online financing form uses the same procedure.
Even with a preliminary approval, final financing can require identity checks, income verification, and confirmation of vehicle details. Read all financing documents before agreeing to a loan. That way, the final obligation matches the terms you reviewed.
Information and Documents to Prepare
A complete application starts with accurate information. For this reason, lenders need enough detail to verify your identity and assess whether the proposed payments are affordable. They may request supporting documents during the first application or later in the process. Therefore, gathering common records beforehand can prevent avoidable delays.
What should you keep ready? These are common examples. However, an individual lender may ask for different items:
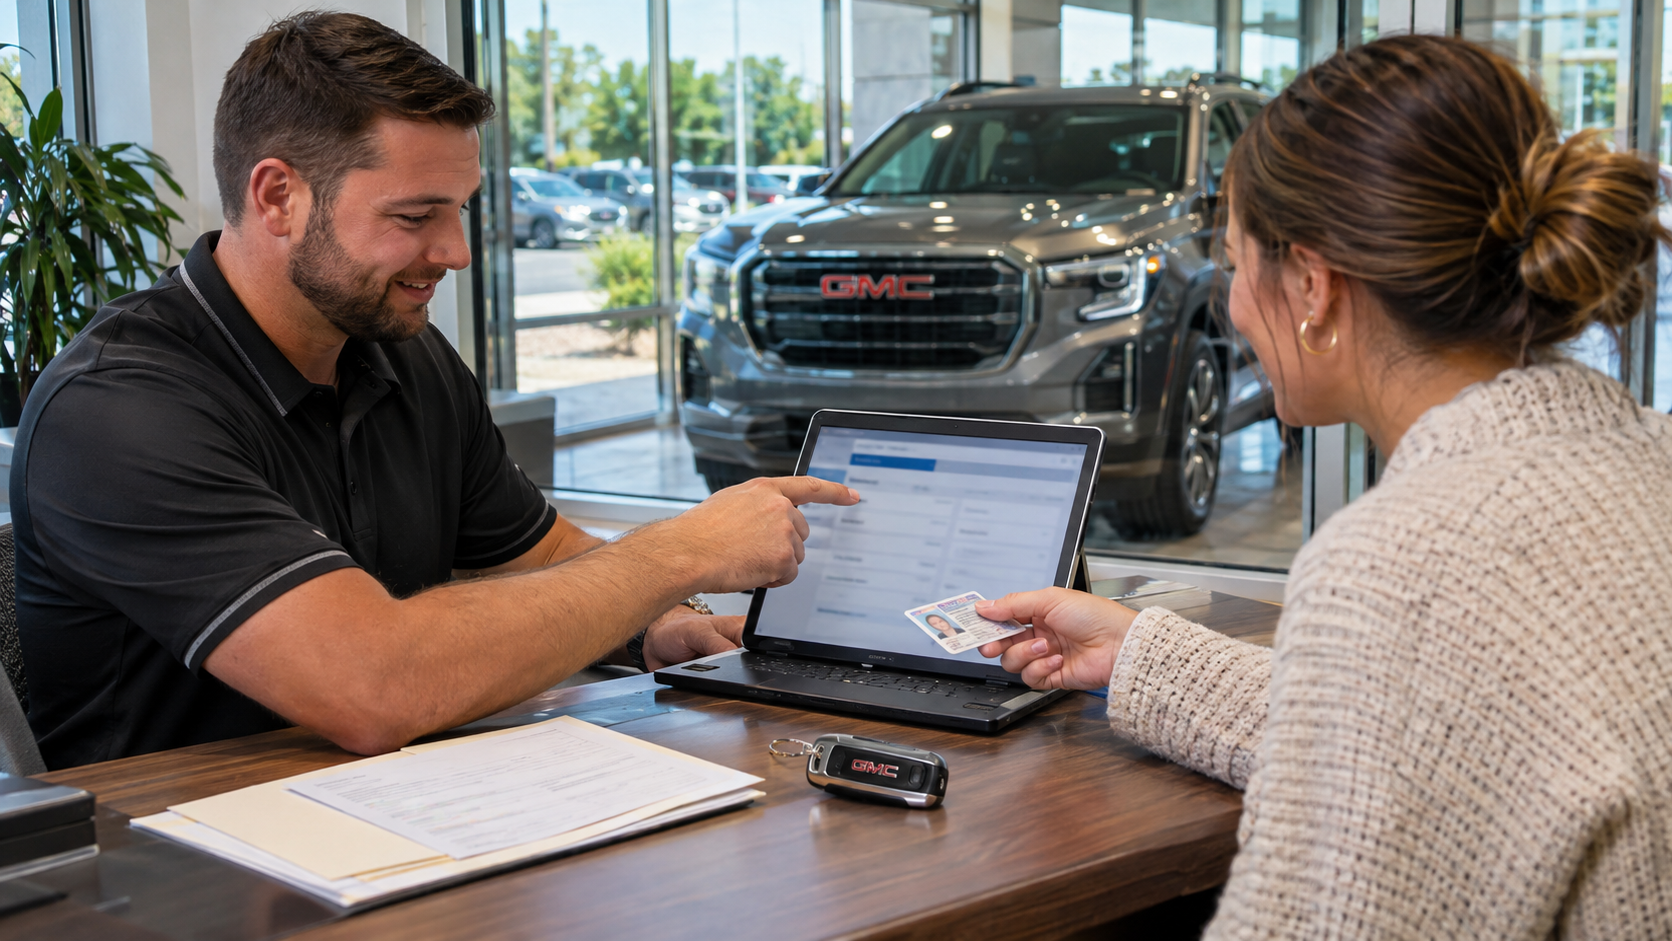
- Identification and residence: Keep a current government-issued ID and your address history available. A lender may request proof of residence.
- Employment and income: Know your employer information and income amounts. Recent pay statements or other income records may be requested.
- Current obligations: Be ready to provide requested housing costs and existing debt information accurately. These details inform the lender's review.
- Vehicle and trade details: If you have selected a GMC, note its price and identifying information. For a trade, have ownership and payoff details ready.
Additionally, some applicants earn income through self-employment or several sources. In that case, the lender may request different records to verify earnings. Do not submit sensitive documents through an unverified email or message. Instead, ask the finance team which secure submission method to use.
Before beginning, review your entries for accuracy. For example, small mistakes in names, dates, or income figures can create follow-up questions. Also, keep copies of any disclosures or loan terms you receive for later comparison.
Financing New and Used GMC Vehicles
Still, new and used vehicles can qualify for different lending terms. A lender reviews the applicant's finances alongside details about the vehicle securing the loan. Therefore, approval for one GMC does not guarantee identical terms for another. Vehicle price, age, mileage, and assessed value may contribute to the final decision.
For example, consider a new GMC Terrain and a used Terrain with several years of road use. Their prices may differ, but purchase price is only one part of the loan evaluation. A lender might apply different loan lengths based on the used vehicle's age and mileage. Any specific restriction must come from the lender, not an assumption about the model.
Likewise, the same reasoning applies when comparing a new GMC Sierra with a preowned truck. Consequently, a higher purchase price may require borrowing more money after your down payment and trade value. In addition, an existing loan on your trade may change the amount you need to finance. Ask for a breakdown showing the trade allowance, payoff, taxes, fees, and resulting loan amount.
Should you choose the vehicle before requesting financing? You can start exploring financing first, but final terms may require a selected vehicle. That makes preliminary research useful without treating an estimate as a guarantee. Once you narrow the models, review the specific numbers for each GMC.
Reviewing Loan Terms Before Making a Decision
A monthly payment shows what comes due each month, but it does not show the full borrowing cost. Therefore, to evaluate an offer, examine the amount financed, annual percentage rate, loan length, and total payments. The APR reflects the annual cost of credit, including certain finance charges. Therefore, it provides a more complete comparison than the interest rate alone.
How can two offers have different monthly payments? For example, a longer repayment period spreads the principal across more payments. That can reduce each payment while increasing total interest paid. Likewise, a larger down payment reduces the amount borrowed, assuming the remaining loan terms stay the same.
Review these figures together before choosing an offer:
- Amount financed: Check how price, down payment, trade value, taxes, fees, and trade payoff shape the loan principal.
- APR and loan term: Compare the annual borrowing cost and number of payments, not the monthly figure alone.
- Total of payments: Review what you would pay across the full loan term and identify any optional products included.
Also, read the contract for late-payment terms and any applicable prepayment provisions. If a figure seems unclear, request an explanation before signing. The Vince's GMC finance department is a relevant next stop for discussing application questions and available financing options. Rates and decisions are subject to lender review and the applicable offer terms.
Preparing for Your Finance Discussion in Burlington
Before you contact the dealership, you should know what you want to finance and which documents may be needed. Start with a realistic vehicle price range and a monthly amount you can manage. Then compare the total loan cost, not only the payment you see first.
Can you begin before arriving in Burlington? Vince's GMC provides an online preapproval page for shoppers ready to begin. Review the application disclosures, confirm what information is required, and submit details only through the dealership's official website. If you have questions first, use the finance department page to find the dealership's contact options.
Additionally, bring any requested records when you visit. Additionally, note questions about down payments, trade equity, loan length, or financing a used GMC. Ask the team to explain any terms you do not recognize before you agree to them. As a result, clear answers now make it easier to compare your options later.
Whether you are considering a Sierra for hauling or a Terrain for daily trips, financing should fit your budget. Therefore, prepare your information, explore the application, and discuss the final figures with Vince's GMC in Burlington, Colorado.